For most people, it's better to wait and apply for a 0% intro APR card shortly before your January expense, because the intro period usually starts when you open the account, not when you make the purchase. Every month you wait to spend is a month of interest-free time you've already used up. The exception is when you're worried the right offer will go away or you need time to line up a plan, and even then you can apply a few weeks early rather than several months early. The smartest way to decide is to start from the date you want the balance paid off and count backward.
Key Takeaways
- The 0% intro APR clock usually starts when the account opens, so applying months early can waste part of the interest-free window.
- Work backward: pick your payoff date, divide the purchase by the months you'll have, and apply close enough to the purchase that the window covers it.
- Applying a few weeks before the expense is a reasonable middle ground; applying many months early mostly just gives you an unused account.
Why does the timing of a 0% intro APR card matter?
A 0% intro APR card gives you a set number of months without interest. For purchases, that period usually begins the day your account is opened. It doesn't wait for your first swipe. Compare current offers.
So if you open a card in September and don't spend until January, you've burned about four months of the window on nothing. If the card has a 15-month intro period, you really only have around 11 months left to pay off your January expense.
Intro periods are also fairly standard. More than 99% of promotional offers in 2023 and 2024 had a 0% introductory period lasting between six and 21 months.[1] That means you're choosing from a limited range, and every month you waste is a bigger share of what you get.
Already know what you want? Timing matters as much as the card itself. Here's how to pick your application date by working backward from your payoff deadline.
Learn MoreHow do you work backward from your payoff deadline?
Start at the end. Decide the month you want the balance gone, then count back to find how long your window needs to be.
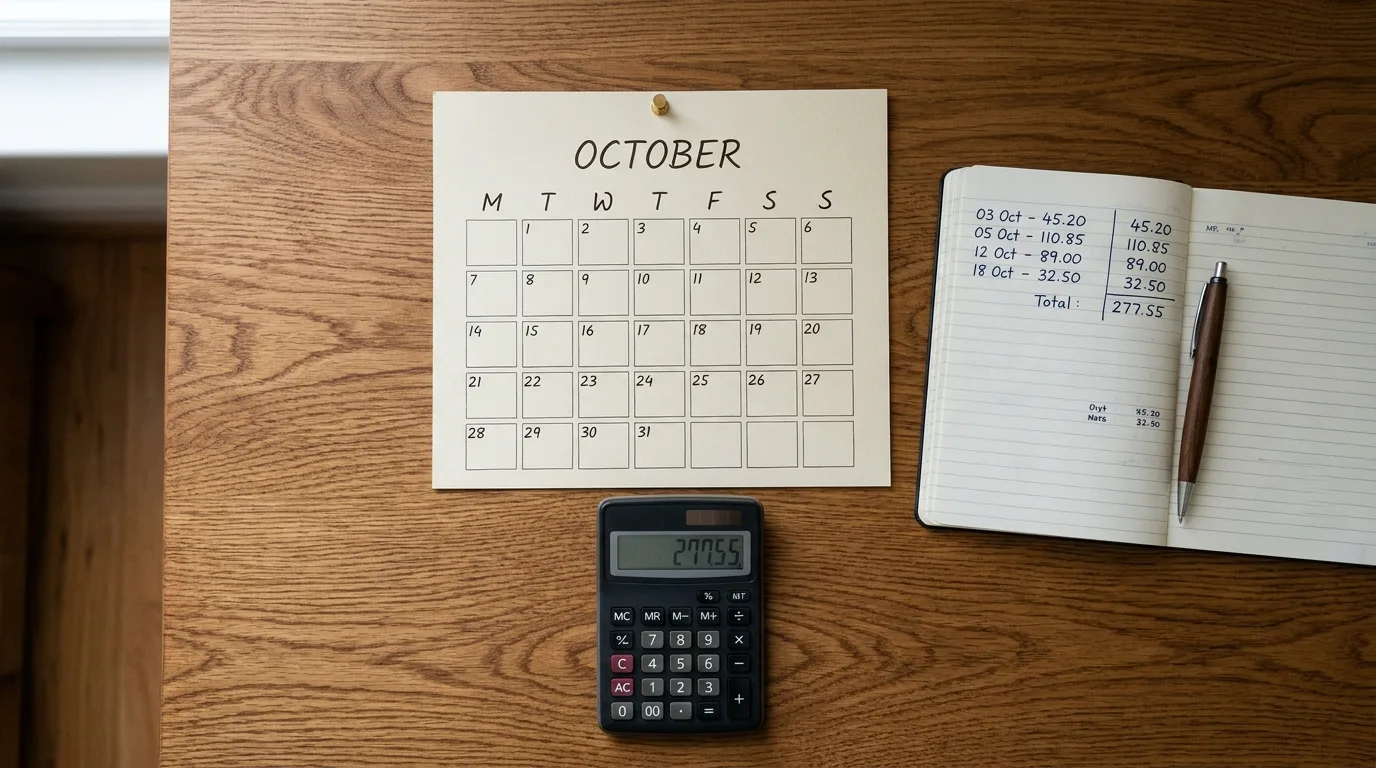
Here's a simple example. Say your January expense is $3,600, and you want it paid off before the intro period ends. If the card gives you 12 months from account opening and you apply in December, then charge the expense in January, you have about 11 months left. $3,600 divided by 11 is roughly $327 a month.
Now say you applied four months earlier, in August. By January, only about 8 months remain. The same $3,600 now needs $450 a month. Same card, same expense, but a much heavier payment, just from applying too early.
Run this math before you apply. If the monthly payment doesn't fit your budget, a longer intro period or a smaller purchase is the safer path.
- Pick the month you want the balance paid in full.
- Count back the intro months a card offers from the day you'd open it.
- Subtract the months between opening and spending.
- Divide the purchase by the months that remain.
Aim to finish paying one or two months before the intro period ends. That gives you room if a payment posts late or your budget gets tight.
Choosing a card early and applying later keeps your options open without using up the intro period.
Is it risky to wait and apply later?
Waiting has a real downside: you can't control what card offers look like in a few months. An offer you like today could change, and the intro period might be shorter or the card might have different terms.
Your own situation can change too. A new loan, a higher balance on another card, or a missed payment before you apply could affect which cards fit your credit. These cards are generally recommended for good to excellent credit, so protecting your credit between now and then matters.
The practical fix is to do your research now and apply later. Pick the card you'd want, note the intro length, and set a calendar reminder for a few weeks before the purchase. If the offer has changed by then, you'll still know what to compare it against.
No Annual Fee Offers
Ready to see what's out there?
What does it cost to carry a new account early?
Opening a card early means you carry an extra account for months before using it. That's not automatically a problem, but there are small costs.
A new account and the hard inquiry that comes with it can nudge your credit score. New credit accounts and inquiries together make up about 10% of a FICO Score, and a new hard inquiry typically lowers a score by only a few points.[2] That's a small effect, but if you're planning to apply for a mortgage or auto loan in the same stretch, it's worth keeping in mind.
There's also the risk of using the card for other things. If you swipe it for groceries in the months before your big expense, that balance can crowd your payoff plan. A no annual fee card at least means holding it early doesn't cost you a yearly charge, but it's still a good idea to keep it for the planned purchase only.
When does applying early make sense?
There are a few situations where a bit of lead time helps. If the expense might come sooner than January, such as a deposit or a first payment due in the fall, having the card ready lets you use the intro period without scrambling.
It also makes sense if you want to see your credit limit before committing to the purchase. If the limit is too low for the expense, you'll learn that with time to spare and can adjust your plan.
Even then, think weeks, not months. A short head start gives you a buffer without giving away much of the interest-free window.
Also remember that intro offers are everywhere. In December 2024, 52.8% of general-purpose credit-card balances were still within an introductory promotional period.[3] These offers are common, so you probably don't need to rush out of fear of missing the only one.
If your expense is more than two months away, wait. If it's within a month or two, it's reasonable to apply now and get your paperwork done.
Compare Current Offers
Check Out Top Offers Available Now
Look at no annual fee 0% intro APR cards and compare the length of the intro period against your payoff plan.
Dividing the purchase by the months you'll have left turns a vague plan into a monthly number.
Learn More About Top OffersFrequently Asked Questions
Should I apply now or wait until closer to my January expense?
What's the risk of waiting?
How do I work out when to apply?
Does the 0% intro APR period start when I open the card or when I buy something?
Will opening a card early hurt my credit?
What if my expense ends up costing more than my credit limit?
What happens if I don't pay it off before the intro period ends?
The Bottom Line
If your expense is months away, wait to apply. A 0% intro APR card is most useful when the whole interest-free window is available for your payments, and applying early quietly shrinks it.
Do the research now, pick your payoff date, and apply a few weeks before you spend. Divide the purchase by the months you'll have, make sure the payment fits your budget, and you can use the intro period the way it's meant to be used.