For most pre-revenue startups, using several business cards as your main funding source is a risky plan, and one card for real, planned expenses is the safer move. The main reason is that you will most likely be personally on the hook for every dollar, while no sales exist to pay it back. This article walks through the risks, a simple way to test your plan, and the situations where a card is the wrong tool entirely.
Why is card stacking riskier before you have revenue?
Card stacking means opening several cards, often to collect sign-up bonuses or to get a bigger total credit line. With a running business, the monthly bill comes out of sales. Before revenue, the bill comes out of your savings, your day job, or the next card. Compare current business card offers.
That last one is the trap. If you pay Card A with Card B, you are not paying the debt down. You are just moving it around, and interest and fees keep building. Many startups are in this position early on: more than half of U.S. startup firms were operating at a loss in the 2023 survey.[1] Losing money early is normal, but it means the card is not being repaid by the business.
A simple rule helps. If you can't say where this month's payment will come from without using another card or a hopeful sales forecast, that spending doesn't belong on a card yet.
Already know what you want? Before you stack cards on a startup with no sales, see which risks matter most and how to test your plan.
Learn MoreWhat does a personal guarantee mean for you?
A personal guarantee means you promise to repay the debt yourself if the business can't. For a new company with no track record, issuers often rely on the owner's finances rather than the business's. So the line between business debt and your own debt is thinner than many founders expect.
This is common across small business lending. Among U.S. employer firms with debt, 59% used a personal guarantee to secure that debt.[2] It is a normal part of borrowing, but normal does not mean harmless.
Here is the practical effect. Say you charge $6,000 across three cards for equipment, software and a website, and the startup earns nothing for six months. That $6,000 is still yours to repay, and late payments can hurt your personal credit. Read the card terms for how the issuer reports activity and what the guarantee covers before you apply.
Look in the cardholder terms for the words "personal guarantee" or "personally liable." If you can't tell who is responsible for the balance, don't apply until you can.
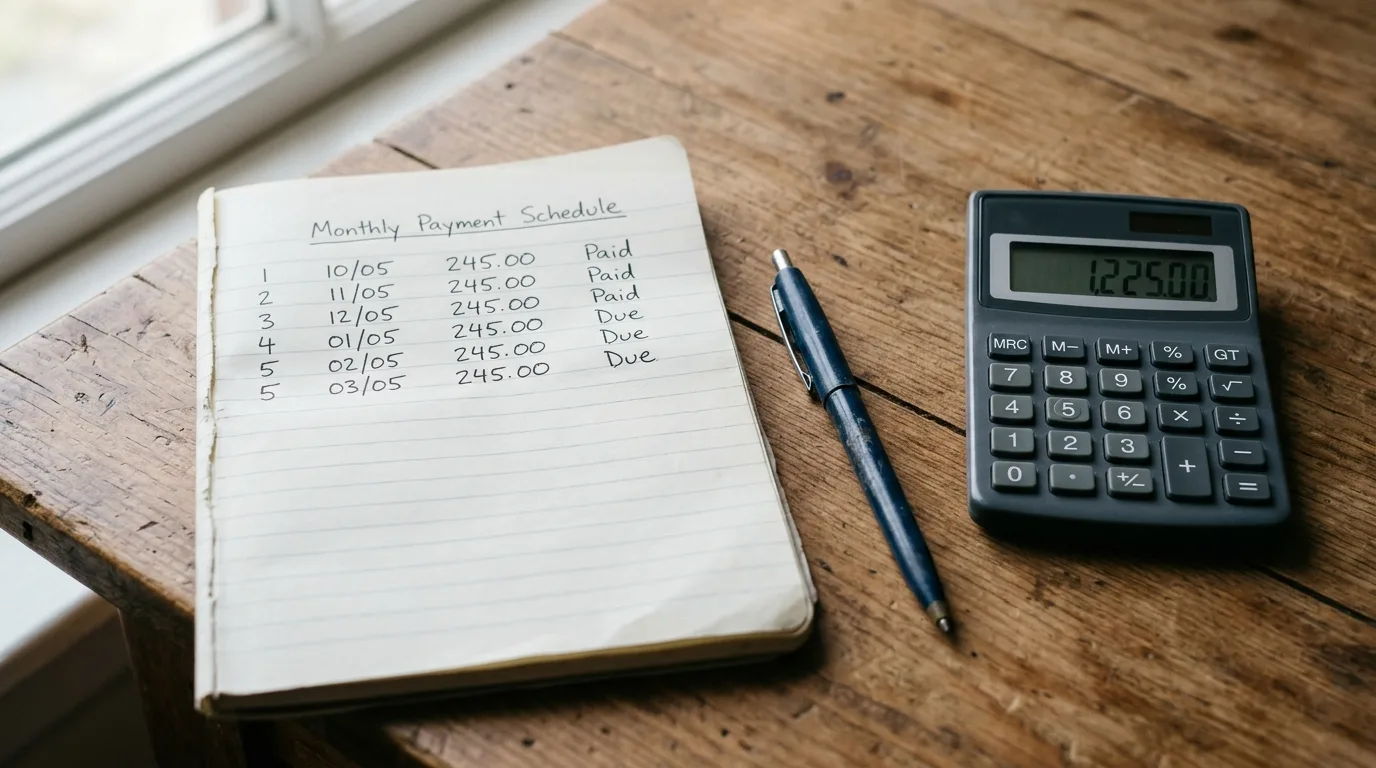
Dividing a purchase by the months you have shows whether the monthly payment is realistic.
How do multiple cards affect utilization?
Utilization is the share of your credit limit you are using. Keeping it under 30% is a common guideline. With a startup, the temptation is to charge a lot quickly, which can push balances high against the limits.
The numbers can look bad fast. A new card might come with a $5,000 limit. Spend $4,500 on it and you are at 90%. Federal Reserve Bank of New York research found that among current borrowers, those with 90%–100% credit-card utilization had a median total credit limit of $5,000, compared with $21,000 among borrowers with 0%–20% utilization.[3] In plain terms, maxed-out borrowers tend to have much less room to begin with.
More cards can spread your balance and lower the percentage on paper, but only if you spend the same amount. If more cards simply means more spending, you have more debt, not better utilization. Also remember that how a business card is reported to credit bureaus varies by issuer, so you can't count on it staying off your personal report.
Business Cards Offers
Want to see what business cards are out there?
| Situation | Card a good fit? | Why |
|---|---|---|
| Software and ads you can pay off monthly | Often yes | Predictable cost with a clear payoff plan |
| Equipment with a 0% intro APR period and a set payment plan | Possibly | Works if the monthly payment fits your budget |
| Payroll with no income yet | No | Debt grows without a source of repayment |
| Paying one card with another | No | Moves the debt without reducing it |
| Long product development with an uncertain budget | Usually no | No clear payoff date |
How should you plan repayment timing?
Cards work best when you know the payoff date before you swipe. A 0% intro APR period can give you time, but it ends, and any balance left then starts collecting interest at the regular APR.
Try this test. Divide the purchase by the number of months you have. A $4,800 purchase with a 12-month 0% intro APR period needs $400 a month to be cleared in time. If $400 a month would come from your own paycheck, ask whether you can keep that up for a year even if the startup earns nothing.
If the answer is yes, that card could help you spread out a planned cost. If the answer is "I'll pay it when sales come in," the card is acting as a bet on revenue. That is where stacking goes wrong, because each new card adds another due date.
- Match each card to one planned expense.
- Write down the monthly payment and where it comes from.
- Pay at least the statement balance by the due date to avoid interest on new purchases where a grace period applies.
- Don't use one card to pay another.
When is a card the wrong tool for startup funding?
Some costs just don't fit a credit card. If you can't answer the question "when will I pay this off?", consider another route first.
Here are the red flags:
- You would need cards to cover payroll or rent with no income expected for months.
- The expense is large and uncertain, like a long product build.
- You are using cash advances or balance transfers to keep other cards current.
- You would need to open many cards in a short time just to reach the amount you need.
- You would struggle to repay the balance from personal income if the startup fails.
Open one card for planned, recurring costs like software or ads, keep spending well under the limit, and pay in full. Build a record before you consider adding more. Many founders also use both business and personal cards: 34% of firms that regularly used a credit card used both.[4] Keeping them separate for bookkeeping is a good habit either way.
So what is a reasonable plan?
Start by listing what you actually need to buy in the next three to six months. Total it. Then compare it with the cash you could put toward repayment without any revenue.
If that cash covers the list, one card with a good fit for your spending could be enough. If it doesn't, the gap is a funding problem, and more cards won't fix it. Look at savings, partners, investors, or other financing first. Then use cards for what they do well: short-term, trackable purchases you can pay off.
Compare Current Offers
Ready to look at your options?
If you have a repayment plan in place, check out top business card offers available now and compare them side by side.
Reading the terms for a personal guarantee before applying is one of the most important steps for a new founder.
Learn More About Top OffersFrequently Asked Questions
Should a pre-revenue startup use multiple business credit cards?
Who is responsible for business card debt if the startup fails?
When is a card the wrong way to fund a startup?
Does a 0% intro APR card help a startup with no revenue?
How much of my limit should I use?
Is it better to use a personal card or a business card?
What are alternatives to card stacking?
The Bottom Line
Using multiple business cards to fund a pre-revenue startup is usually a risky plan, mainly because you are likely personally responsible for the balances while no sales exist to pay them. One card for planned, repayable costs is a safer way to begin.
Before you add any card, write down the expense, the payoff date and where the payment will come from. If you can't fill in all three, wait. When you are ready, you can compare current offers and choose a card that matches your plan.