Usually not: a business credit card typically requires an organization that legally exists and has an EIN, so before that, most founders cover startup costs with a personal card or cash and track every charge. The good news is that this is a normal, workable path. If you keep clean records, the organization can usually reimburse you once it has its own bank account, and then you can look at a card in its name.
Key Takeaways
- Business card applications generally ask for a legal entity and an EIN, so before your organization is formed, a personal card (or a fiscal sponsor) is the usual way to pay startup costs.
- Put pre-launch charges on one card and log each one with the date, amount, and purpose, so the organization can reimburse you later.
- Once the organization has its EIN and bank account, move ongoing spending to a business card in its name and stop using your personal card.
Why can't you get a business card before the organization exists?
A business card is issued to a business or organization. The application usually asks for a legal name, an EIN, and some proof the entity exists, such as formation documents filed with your state. Before you file, none of that exists, so there's nothing for a lender to attach the card to. Compare current business card offers.
That leaves you with a timing problem. You need to spend money to create the organization, but the tools built for organizations aren't available until it exists. It isn't a sign you're doing something wrong. It's just the order things happen in.
This page is for nonprofits and groups that aren't incorporated yet. If you're starting a for-profit company, the rules and options can be different, so a for-profit founder should look at guides built for that.
Already know what you want? Paying for filings, a website, and other startup costs before your organization exists takes a plan. Here's how to handle it and what to do once you're official.
Learn MoreHow do you pay startup costs before the organization exists?
You have three realistic options, and many founders combine them.
The most common is paying personally. That's a common way new ventures start: 83% of U.S. business owners reported using personal assets to cover startup costs, and credit cards were the second-most common startup funding source.[1] Personal assets or credit cards also made up 63% of startup funding, compared with 19% from bank or government loans.[2] You're in the majority if you start this way.
The second option is a fiscal sponsor. This is an established organization that lets your project operate under its legal and tax umbrella while you get going. A 2023 field scan estimated that between 500 and 5,000 fiscal sponsors were active in the United States.[3] The sponsor holds the money and pays the bills, so you may not need to front costs yourself. Sponsors set their own terms and fees, so ask before you sign.
- Personal card or cash: simple and fast, but you carry the cost until you're reimbursed.
- Fiscal sponsor: the sponsor handles the money, but you give up some control and may pay a fee.
- Donations or founder contributions in a separate account: can help, but be careful about how funds are held and reported before the organization exists.
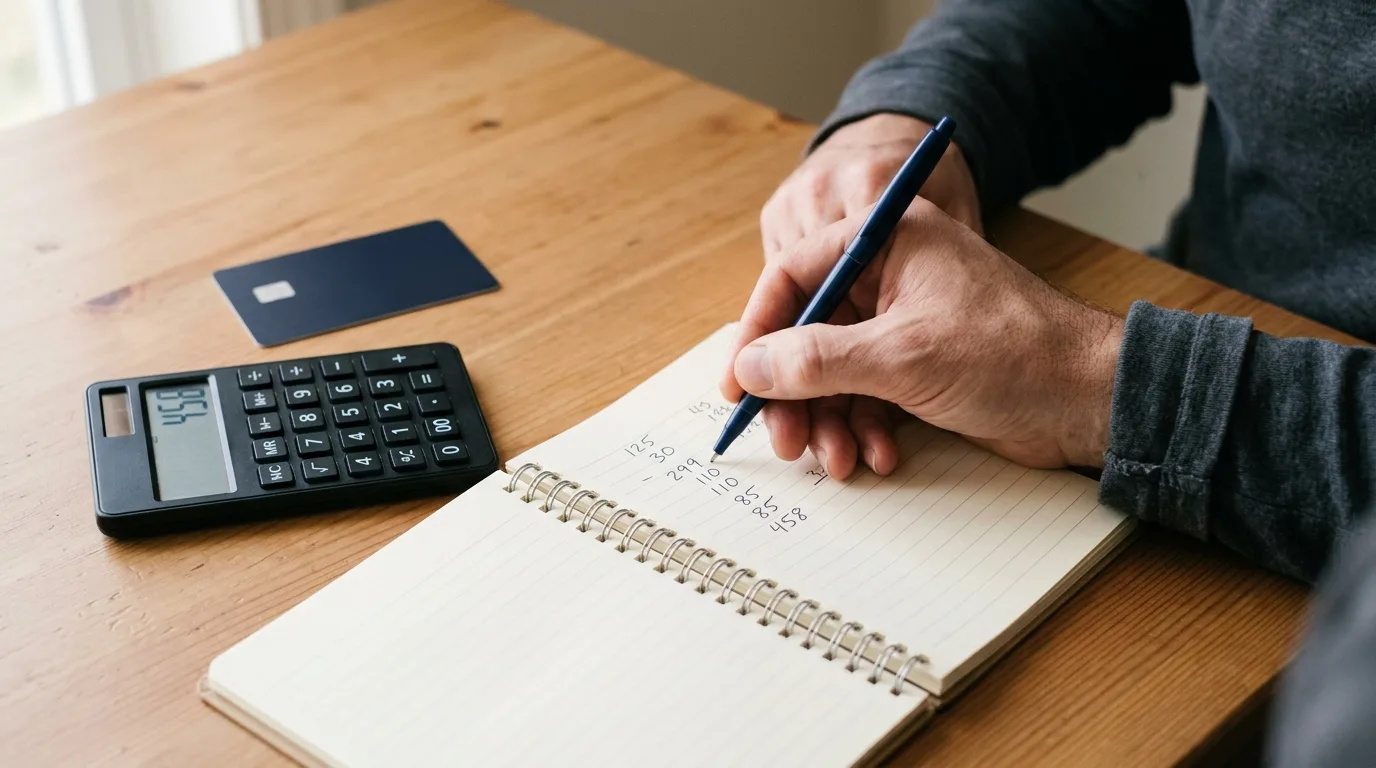
A simple log of dates, amounts, and purposes is what makes reimbursement straightforward later.
Which personal card makes sense for pre-launch costs?
Think of this card as a short bridge, not a long-term tool. A card with no annual fee is usually the sensible fit, since you don't want to pay a yearly cost for something you'll use for a few months.
Timing decides the rest. Say you expect about $1,200 in filing, legal, and website costs over the next few weeks. A card with a 0% intro APR period could give you room to pay that down over several months without interest, as long as you pay it off before the intro period ends. If your costs are small and spread out, a no annual fee cash back card might fit better, since you'd pay it off each month. Earning 2% back on $1,200 is $24, a small perk on money you're getting back anyway.
Whichever you pick, use it only for the organization's costs if you can. Mixing them with groceries and gas makes the reimbursement log harder to build. Cards like these are generally recommended for good to excellent credit.
If you use a 0% intro APR card, divide the total by the number of intro months and make sure that monthly payment fits your budget. Whatever is left when the intro period ends starts collecting interest at the card's regular APR.
Business Cards Offers
Ready for a card once your organization is official?
| Your situation | Practical way to pay | Watch out for |
|---|---|---|
| Not formed yet, small costs | Personal no annual fee card, paid off monthly | Keep charges separate and logged |
| Not formed yet, several costs at once | Personal card with a 0% intro APR period | Plan to pay it off before the intro period ends |
| Want someone else to hold the money | Fiscal sponsor | Terms and fees vary by sponsor |
| Formed, EIN and bank account in place | Business card in the organization's name | Compare terms and requirements before applying |
How do you keep track so you can get reimbursed?
Start a simple log the day you spend your first dollar. Record the date, amount, who you paid, and what it was for. Save receipts and invoices in one folder.
Once the organization exists and has a bank account, its board can approve paying you back. A clear log makes that vote easy, and it gives anyone who reviews the books later, such as a donor or grantmaker, a clean paper trail.
Check the details for your situation, since reimbursement rules and tax treatment can vary. A local accountant or attorney who works with nonprofits can confirm how to document it.
- Date of the charge
- Amount and payee
- Purpose (state filing, legal help, website, and so on)
- Receipt saved, yes or no
- Date reimbursed
What should you do once the organization exists?
Move in this order. First, finish formation with your state. Second, get your EIN. Third, open a bank account in the organization's name. Fourth, reimburse yourself from that account, using your log.
After that, you can look at a business card for the organization. Having an EIN, a bank account, and a short record of spending may help when you apply, though requirements vary by issuer. Then move ongoing costs like software, supplies, and program expenses to that card, and stop using your personal one.
Separating the two early keeps your personal card out of the organization's day-to-day spending and makes the books easier to read.
Compare Current Offers
Set up a card for your organization
Once you have an EIN and a bank account, check out top offers available now for new organizations.
Once the organization is official, reviewing the paperwork is the first step toward opening its own bank account and card.
Learn More About Top OffersFrequently Asked Questions
Can I get a business card before my nonprofit exists?
Who pays for startup costs before the organization is official?
What should I do once the organization exists?
What is a fiscal sponsor, and can it help?
Should I use a 0% intro APR card or a cash back card?
Do most new ventures really start with personal money?
Should I keep nonprofit charges on a separate card?
The Bottom Line
You don't need a business card to start an organization. You need a plan: pay for formation costs with a personal card or through a fiscal sponsor, track every charge, and don't let the spending blur with your personal budget.
Once your EIN and bank account are in place, reimburse yourself from the organization's account and compare business cards in its name. That's when it can start handling its own spending.