A local HVAC supply house might code a furnace or condenser purchase as wholesale trade rather than home improvement, so a category bonus may not apply. The payment processor determines the merchant category code, not the supply house owner or the customer. For a large equipment purchase, a flat-rate card offers a more predictable reward than a category bonus that might not trigger.
Key Takeaways
- Merchant category codes are set by the payment processor, not the store, so you can't be sure in advance whether an HVAC supply house will code as 'home improvement'
- A flat-rate cash back card earns rewards regardless of how the merchant is coded; category cards depend on the code matching the bonus category
- For a one-time large purchase, consider calling the supply house's billing office to ask how they process cards before assuming any bonus category applies
Why merchant category codes trip people up
Every business that accepts cards gets assigned a merchant category code, or MCC, by whichever company processes its payments. That code tells your card issuer what kind of business just charged you — grocery store, gas station, home improvement store, wholesale distributor, and so on. compare flat-rate cash back offers
The problem is that the business itself doesn't always control this. A supply house that sells furnaces, condensers, and ductwork to contractors might get filed under 'wholesale trade' or 'building materials' instead of 'home improvement store,' depending on how its processor set things up years ago. Two supply houses in the same town, selling nearly identical equipment, can carry different codes.
You can't confirm the code just by looking at the storefront or website. You can ask the business, check whether your card issuer provides category information for past transactions, or make a small test purchase and see how it posts. A test purchase may not guarantee a larger transaction will be categorized the same way.
Already know what you want? Before you buy HVAC equipment on a new card, find out whether the reward you're expecting is guaranteed or just hopeful.
Learn MoreThe guaranteed bet: flat-rate cash back
A flat-rate card earns its stated rate on the purchase regardless of the supply house's merchant code. A category card with a higher rate for home improvement purchases may earn more, but only if the transaction codes correctly. If it doesn't, you may earn only that card's base rate, which could be lower than the flat-rate card's return.
This is the core tradeoff: category cards offer a higher potential return but depend on the merchant code, while flat-rate cards offer a more predictable return. For a single large, uncertain purchase, that predictability may be worth more than the chance of earning more.
Cash back is a popular rewards option: 58% of U.S. credit-card customers reported using cash-back cards in 2024, compared with 31% using points-or-miles cards.[3]
If you're set on a category card, consider making a small, refundable test purchase and checking how your card account labels the merchant. If it appears in the bonus category, that may be a useful indication, but it doesn't guarantee the larger purchase will code the same way.
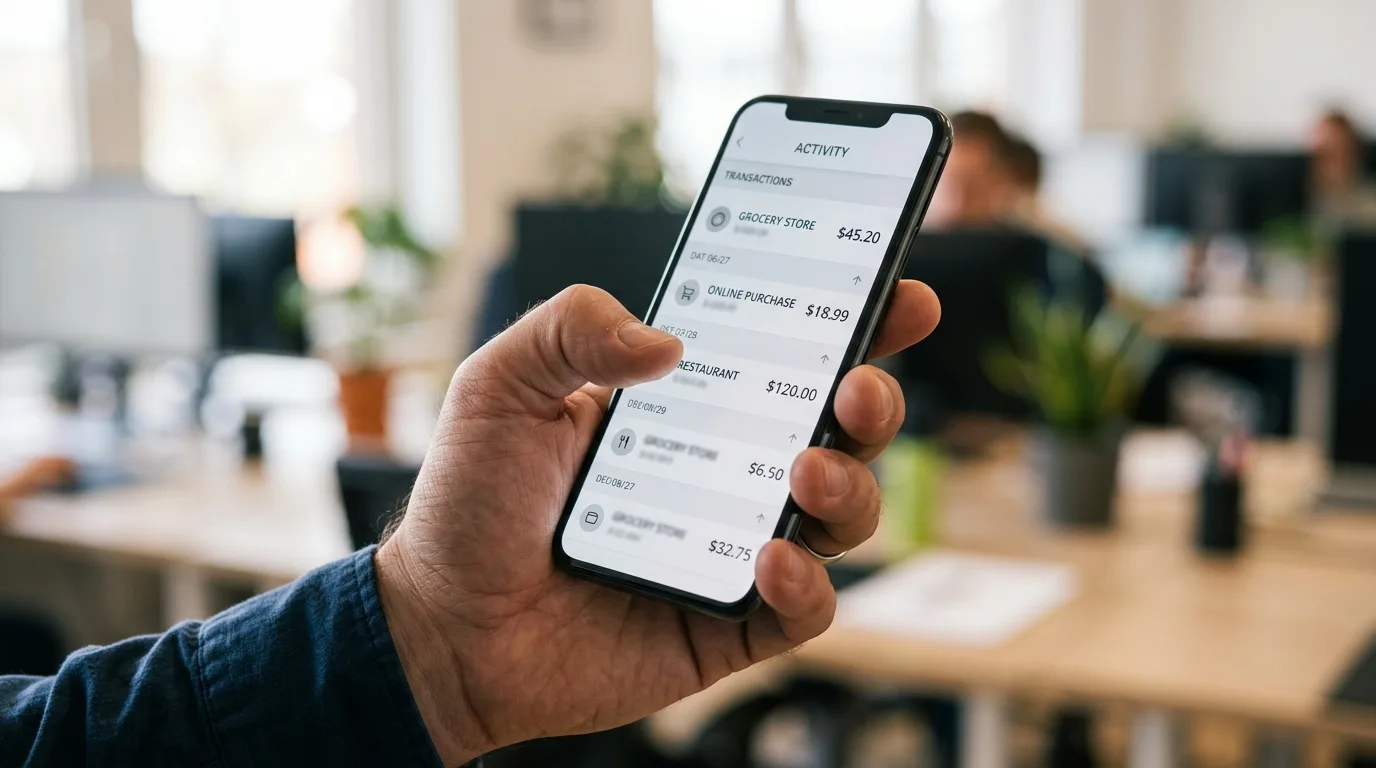
Checking how a purchase posts in your card's app can reveal its merchant category.
When a category card is still worth the gamble
If you already know — because you asked, or because a past purchase at that same supply house posted correctly — that the merchant does code as home improvement, then a category bonus card can genuinely outperform a flat-rate card on this purchase. The math only favors the category card when the higher rate is confirmed, not assumed.
Some people split the difference: they open a flat-rate card as their default and keep a category card in reserve for purchases they've already verified will code favorably. That way the guaranteed option handles the uncertain stuff, and the higher-earning option only gets used where it's proven to work.
One more wrinkle worth knowing: some category cards define 'home improvement' narrowly, excluding wholesale distributors or contractor-only supply houses even when the code is technically right. Read the card's own terms for how it defines the bonus category, not just the general label.
Cash Back Offers
Not sure which cash back structure fits a big one-time purchase?
| Scenario | Flat-rate cash back card | Category bonus card |
|---|---|---|
| Merchant codes as home improvement | Earns standard flat rate | Earns higher bonus rate |
| Merchant codes as wholesale/other | Earns standard flat rate (no change) | Earns only the card's base rate, often lower |
| You're unsure how merchant codes | Reward is certain either way | Reward is a gamble either way |
What if you're financing the equipment instead of paying it off right away?
If you plan to carry a balance, the reward rate may matter less than the interest you could pay. Nearly half of U.S. credit-card adopters carried an unpaid balance in 2024; among those who revolved balances, the median unpaid balance was $2,600.[2] If you expect to carry the equipment purchase, a 0% intro APR card could help you save on interest, potentially more than a cash-back reward. Check the card's terms, including what happens after the introductory period.
In that case, the merchant-code question becomes secondary. You may want to compare 0% intro APR cards and their introductory periods, and consider any cash back as a secondary benefit rather than the main reason for your choice.
If you're confident you'll pay it off within a billing cycle or two, the reward-rate comparison above is the one that matters most.
How complaints and rewards rules play into this
The CFPB received more than 1,200 complaints involving credit-card rewards in 2023, an increase of more than 70% from pre-pandemic levels.[4] In 2024, 36% of U.S. general-purpose credit-card accounts offered cash-back rewards, while 20% offered no rewards; consumers earned $47.5 billion in credit-card rewards overall.[1]
That scale is a reason to check the terms carefully. A category bonus may not apply to every merchant that appears to fit the category, so treat it as a possible upside until you confirm how your specific purchase is classified.
Compare Current Offers
Ready to pick a card before your HVAC purchase?
Compare flat-rate and category cash back cards side by side before you commit to a payment method for your equipment purchase.
Confirming details with the supply house before buying can save a guessing game later.
Learn More About Top OffersFrequently Asked Questions
Will an HVAC supply house definitely code as a home improvement store?
What's the safer card choice for a big HVAC purchase if the category is uncertain?
Can I find out the merchant category code before I buy?
Does it matter who owns the supply house for how it codes?
Should I just open a 0% intro APR card instead of worrying about rewards?
Can I combine a flat-rate card with a category card?
Is it worth calling the supply house to ask about their merchant code?
The Bottom Line
You can't control how a supply house's payment processor codes the sale, so don't build your card strategy around a bonus category you haven't confirmed. For a purchase this size, a flat-rate cash back card gives you a reward you can count on no matter what the receipt says behind the scenes.
If you can verify ahead of time that the merchant codes favorably, a category card may earn more. If you can't verify it, or you're planning to carry a balance, a flat-rate card may offer a more predictable reward; if financing is the bigger concern, compare 0% intro APR options and their terms.